Your roof claim was approved, the contractor says the replacement will cost $18,000, and the insurance check is only $9,500. Before assuming the insurer shorted the claim, look for lines labeled depreciation, recoverable depreciation, holdback, actual cash value, or replacement cost value.
Quick answer: on many replacement-cost homeowners claims, the first payment is intentionally smaller than the final covered amount. The insurer may initially pay the depreciated value of the covered damage, less your deductible, then release some or all of the withheld depreciation after you complete the covered repair and submit the required documentation. If your roof is covered only at actual cash value, the depreciation may never come back.
Start With These Six Numbers
Find the insurer’s estimate and claim letter and identify six figures or terms: replacement cost value, depreciation, actual cash value, deductible, recoverable depreciation, and the deadline for completing repairs. Together, they usually explain why the first check is smaller than the contractor’s price and whether another payment may be available.
| Line on the estimate | What it usually means |
|---|---|
| Replacement cost value (RCV) | Estimated cost to repair or replace the covered damage with comparable new property at current prices. |
| Depreciation | Reduction for age, wear, condition, or expected useful life. |
| Actual cash value (ACV) | Replacement cost minus depreciation, subject to the policy’s valuation terms. |
| Deductible | The portion of the covered loss you are responsible for under the policy. |
| Recoverable depreciation | The part of withheld depreciation that may be paid later if you satisfy the policy’s replacement-cost conditions. |
| Repair deadline | The date by which the policy or claim process may require you to complete repairs or claim replacement-cost benefits. |
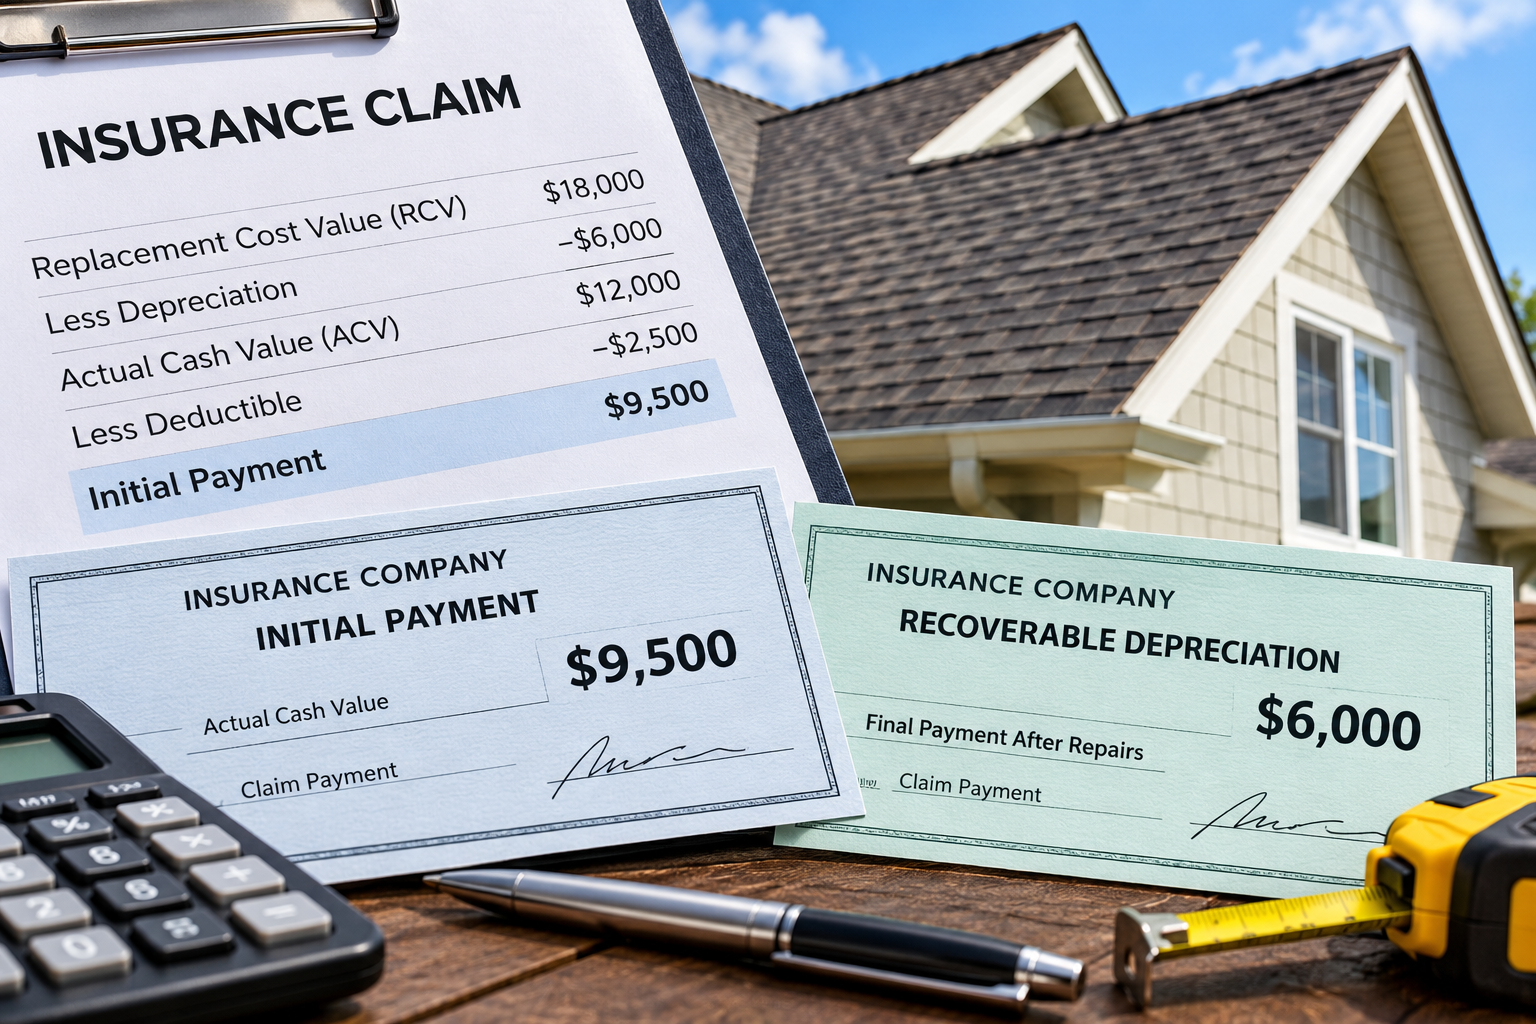
Suppose the insurer estimates that replacing a storm-damaged roof will cost $18,000. It applies $6,000 of depreciation and your policy has a $2,500 deductible. The initial payment might look like this:
- Replacement cost value: $18,000
- Less depreciation: $6,000
- Actual cash value: $12,000
- Less deductible: $2,500
- Initial insurance payment: $9,500
If the $6,000 is recoverable and you satisfy the policy’s conditions, the insurer may later release up to that withheld amount. In this example, total insurance payments could reach $15,500: the $18,000 covered replacement cost less the $2,500 deductible. Your deductible is still your responsibility; it is not part of the depreciation payment.
Why Some Roof Claims Are Paid in Two Stages
Replacement-cost coverage can pay for covered repairs at current prices, but the entire replacement-cost amount is not always released before the replacement occurs. USAA’s current homeowners claims guidance, for example, describes an initial payment based on the depreciated value of covered damage and a possible second payment after repairs are completed. That later payment is commonly called recoverable depreciation or a holdback.
A smaller first check therefore does not necessarily mean the insurer has denied part of an otherwise covered roof claim. It may mean the claim is being paid first at actual cash value, with replacement-cost benefits available after the work is completed and documented.
How to Tell Whether Your Depreciation Is Recoverable
Do not assume every depreciation line will be paid later. Read the estimate, claim letter, declarations page, and any roof or valuation endorsements for wording such as recoverable depreciation, nonrecoverable depreciation, replacement cost, actual cash value, or an age-based roof schedule.
The Texas Department of Insurance explains the basic distinction: replacement-cost coverage pays based on current repair or replacement costs, while actual-cash-value coverage reduces the payment for depreciation. Roof coverage can also change as a roof ages, so do not assume that replacement-cost coverage elsewhere in the policy automatically means the roof itself is covered the same way.
If the roof is covered only at actual cash value for this loss, replacing it does not by itself create a right to recover the depreciation. Before signing a roofing contract on the assumption that another check is coming, ask the adjuster to identify the policy language that makes the withheld amount recoverable.
What You Usually Need to Request the Second Payment
The exact requirements come from your policy and insurer, but the process commonly requires evidence that the covered repair or replacement was actually completed. USAA tells policyholders seeking recoverable depreciation to submit receipts or final invoices so the adjuster can determine whether an additional payment is due.
Ask your adjuster what documentation is required before work begins. Depending on the claim and insurer, that might include a final itemized invoice, proof of payment, completion photos, permits, or other evidence showing what work was performed. Keep copies of everything you submit and ask how the insurer wants the request labeled or uploaded.
Do Not Miss the Repair Deadline
Replacement-cost benefits can be subject to a deadline for completing repairs or requesting the withheld amount. The Texas Department of Insurance advises homeowners that they usually must complete repairs within a certain period and should ask the agent or adjuster if the deadline is unclear.
If weather, contractor availability, permitting, mortgage-company processing, or material shortages make the deadline difficult to meet, contact the adjuster before it expires. Ask whether an extension is available and keep any approved extension or revised deadline in writing.
If the Final Roof Price Is Different From the Insurance Estimate
The insurer’s estimate and the contractor’s final price may not match. If the completed covered work costs less than the insurer estimated, do not assume the full withheld depreciation will automatically be paid; ask how the policy calculates replacement-cost recovery when the final invoice is lower.
If legitimate covered work costs more, the contractor may need to document the difference and submit a supplement. USAA’s claims guidance, for example, tells policyholders to contact the adjuster when additional damage or costs are discovered so the insurer can review a supplemental request.
A supplement and recoverable depreciation solve different problems. A supplement asks the insurer to increase the approved scope or cost of covered repairs; recoverable depreciation is money withheld from the covered amount because the damaged property was depreciated.
What If the Roofer Wants More Than the Insurer Estimated?
Compare the contractor and insurer estimates line by line before treating the entire difference as one dispute. The roofer may have included damaged decking, flashing, underlayment, permit costs, code-related work, or other items that the first insurance estimate did not include.
If additional damage becomes visible after tear-off, document it before it is covered back up and follow the insurer’s supplement procedure. Our guide to whether homeowners insurance covers a roof leak explains how the cause of loss, deductible, roof valuation, and supplemental damage fit into the broader claim.
What If You Cannot Afford to Front the Depreciation?
The two-stage payment process can create a real cash-flow problem. In the example above, the homeowner is responsible for a $2,500 deductible while another $6,000 is temporarily withheld as depreciation, even though the contractor may expect substantial payment before the job is complete.
Ask the roofer whether the payment schedule can reflect the insurance process, and ask the adjuster when the completed work is sufficient to request the withheld amount. Do not sign financing documents, assignments of benefits, or other contracts you do not understand simply because the first insurance check is smaller than the roofing contract.
Why Your Mortgage Company May Be on the Check
If you have a mortgage, the lender may be named on an insurance claim payment because it also has a financial interest in the house. That can add another step before you can use the money for repairs. USAA advises policyholders whose mortgage company is listed on a claim check to contact the lender for its endorsement or disbursement instructions.
Ask early whether the mortgage company will release the money all at once or in stages as work is completed. A lender’s inspection or endorsement process can affect your contractor payment schedule even when the insurance claim itself is moving normally.
Questions to Ask the Adjuster Before You Replace the Roof
A short call can prevent a large misunderstanding. Ask the adjuster to walk through the payment calculation using the insurer’s own estimate, then write down the answers.
- Is my roof covered at replacement cost or actual cash value for this loss?
- How much depreciation has been withheld?
- How much of that depreciation is recoverable?
- What exactly must I submit to request it?
- What is the deadline for completing repairs and claiming replacement-cost benefits?
- If the contractor’s covered scope costs more than your estimate, how do I submit a supplement?
- If the completed repair costs less than the estimate, how will that affect the final payment?
- Does my mortgage company need to endorse or control any claim checks?
If you are shopping for a replacement roof rather than handling an active claim, our guide to whether a metal roof can lower homeowners insurance explains how roof type, impact resistance, age, and insurer rules can affect premiums and coverage.
Before You Count on the Second Check
If an approved roof claim check looks thousands of dollars smaller than the contractor’s estimate, determine whether the gap is withheld recoverable depreciation before concluding that the insurer has underpaid the claim. On a replacement-cost claim, some or all of that money may be payable after covered work is completed and documented. On an actual-cash-value roof claim, depreciation may instead be a permanent reduction in what the policy pays.
Before work starts, make sure you can identify the replacement cost, actual cash value, depreciation, deductible, recoverable amount, and repair deadline on your own claim. If any of those are unclear, ask the adjuster to explain them in writing before you commit to a contractor price based on money you have not yet received.
Write a Reply or Comment